
Insurance for LLCs that Own Real Estate
By Arizona LLC attorneys Richard Keyt (480-664-7478 & rk@keytlaw.com) and his son Richard C. Keyt (480-664-7472 & rck@keytlaw.com). We have formed over 10,000 LLCs and have 432 five-star reviews on Google, Facebook & Birdeye. Book a free office, phone or Zoom consultation.
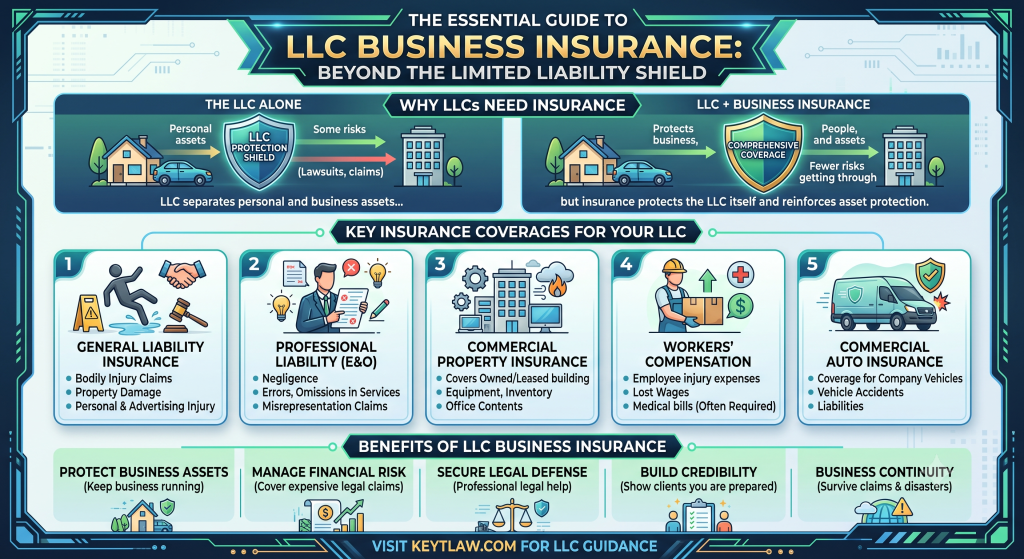
An Arizona LLC that operates a business needs both the LLC and insurance because they protect against different risks. The LLC protects the members’ personal assets from the LLC’s liabilities, but it does not protect the assets the LLC owns, and it does not protect a member from liability for the member’s own acts. A business LLC should buy: (1) commercial general liability coverage of at least $1,000,000 per occurrence and $2,000,000 aggregate, (2) commercial property insurance at replacement cost, (3) workers’ compensation insurance, which Arizona law requires if the LLC has even one employee, (4) commercial auto insurance with a $1,000,000 combined single limit, and (5) a commercial umbrella policy of $1,000,000 or more. Depending on the business, the LLC may also need professional liability (E&O), cyber liability, business interruption, and employment practices liability coverage. The LLC must be the named insured on every policy — a common mistake is forming an LLC for an existing business while leaving the insurance in the individual owner’s name.
You formed an Arizona limited liability company to own your rental house, your duplex, your short-term rental, or your commercial building. Good. The LLC puts a wall between the property and your personal assets. But the LLC is only half of the protection plan. The other half is insurance, and the most common mistake we see is an LLC that owns real estate while the insurance policy still names the individual owner, still covers the property as an owner-occupied home, or has no liability coverage for the LLC at all.
This article explains what insurance an Arizona LLC that owns real estate should carry, whose name belongs on each policy, what changes when you deed property into an LLC, and the coverage gaps that cause claim denials. It covers both residential rentals (single-family homes, condos, duplexes, fourplexes and short-term rentals) and commercial property.
The LLC that owns the property should be the named insured on the property and liability policies. The members and manager should be listed as additional insureds. Call your insurance agent before you record the deed to the LLC, not after. Buy a landlord or commercial policy, not a homeowner's policy. Carry enough liability coverage to protect the equity in the property, and add an umbrella policy that actually covers the LLC. Check what happens to your owner's title insurance policy when title moves to the LLC.
- Why an LLC Still Needs Insurance
- Whose Name Goes on the Policy
- What to Do When You Deed Property to Your LLC
- Insurance for Residential Rental Property
- Short-Term Rentals and Vacation Rentals
- Condos and HOA Property
- Insurance for Commercial Real Estate
- How Much Liability Coverage Is Enough
- Umbrella Policies and the LLC Gap
- Title Insurance After the Transfer
- Workers' Compensation and Contractors
- Coverage Gaps That Cause Claim Denials
- One LLC or Many, One Policy or Many
- Insurance Checklist for a Real Estate LLC
- Frequently Asked Questions
Why an LLC Still Needs Insurance
An Arizona LLC and insurance do two different jobs. They are not substitutes for each other.
The LLC protects your personal assets. Under A.R.S. §29-3304, a member or manager is not personally liable for the debts, obligations or other liabilities of the LLC solely because he or she is a member or manager. If a tenant sues the LLC over an injury at the rental property and wins a judgment larger than the LLC can pay, the tenant generally cannot collect the rest from your home, your bank accounts, or your other LLCs.
Insurance protects the LLC's assets. The LLC shield does nothing to protect the property inside the LLC. If the LLC owns a $600,000 rental house with $350,000 of equity and a tenant wins a $500,000 judgment, the equity in that house is exactly what the tenant's lawyer will go after. Insurance is what pays the judgment and the lawyer who defends the lawsuit, so the LLC keeps the property.
Insurance also covers the things an LLC cannot: a fire, a burst pipe, a monsoon-damaged roof, a vandalized vacant unit, or the months of rent you lose while the property is being rebuilt.
And insurance fills the holes in the LLC shield. The LLC does not protect you from your own negligence. If you personally repair a staircase badly and a tenant falls, the tenant can sue you personally as well as the LLC. A properly written policy that lists you as an insured defends you too.
Whose Name Goes on the Policy
This is where most real estate LLC owners go wrong. The rule is simple: the insured should match the owner.
The LLC should be the named insured
When the LLC owns the property, the LLC should be the first named insured on the property policy and on the liability policy. The exact legal name of the LLC, as it appears in the Articles of Organization filed with the Arizona Corporation Commission, should appear on the declarations page. "Smith Rentals" is not the same as "Smith Rentals, LLC."
The members and manager should be additional insureds
Ask the agent to add each member and the manager as an additional insured for liability arising out of the property and the LLC's business. Plaintiffs' lawyers routinely name the LLC and every person connected to it as defendants. You want the insurance company defending all of you, not just the LLC.
The lender and the property manager
If the property has a mortgage, the lender must be listed as mortgagee (loss payee) on the property coverage. If you use a property management company, it will usually ask to be added as an additional insured on the liability coverage. Your agent handles both with endorsements.
Why the wrong name is a real problem
Arizona's insurable interest statute, A.R.S. §20-1105, requires that a person insured under a property policy have an actual, lawful and substantial economic interest in the property. Once you deed the property to your LLC, the LLC owns it, not you. An insurer that discovers after a fire that its named insured no longer owns the building may argue it owes less, or nothing, or it may pay only after a long fight. On the liability side, a policy that names only you personally may not obligate the insurer to defend the LLC at all, because the LLC is a separate legal person that is not an insured under your policy.
Some carriers will cover the gap if you tell them in time. Some will not. You do not want to learn which kind you have after a claim.
What to Do When You Deed Property to Your LLC
Many of our clients buy property in their own names and later transfer it to an LLC with a special warranty deed. The deed is the easy part. The insurance, the mortgage and the title policy are the parts people forget. Follow this order:
- Call your insurance agent before the deed is recorded. Tell the agent the recording date and the exact name of the LLC. Ask the agent to rewrite the policy or issue a new policy with the LLC as named insured, effective the same day the deed records.
- Change the type of policy if needed. If the property is a rental insured under a homeowner's policy (it happens more often than you would think), this is the time to move it to a landlord (dwelling fire) policy or a commercial policy.
- Keep the lender listed as mortgagee. If the loan stays in your personal name, ask the agent to keep the lender on the policy and to list you as an additional insured so the policy still satisfies the loan documents.
- Get written confirmation. Ask for the new declarations page showing the LLC as named insured. Keep it with the recorded deed.
- Update your umbrella policy. Tell your umbrella carrier the property is now owned by an LLC. See the umbrella section below.
- Check your title insurance. See the title insurance section below.
- Update the leases and the tenants. Assign the existing leases to the LLC, tell the tenants who the new landlord is, and make sure the LLC is named as landlord on every future lease.
Whether the deed triggers the due-on-sale clause in your mortgage is a separate question. The federal Garn-St Germain Act, 12 U.S.C. §1701j-3, does not list a transfer to an LLC among its protected transfers. We cover that issue in detail in Does Transferring Land to an LLC Trigger a Due on Sale Clause? In our experience, keeping the lender listed on the insurance and keeping the loan payments current matter a great deal.
Most transfers of Arizona real property to an LLC owned by the same people are exempt from the affidavit of property value requirement under A.R.S. §11-1134. Arizona has no real estate transfer tax, and a transfer to your own LLC does not cause the county to reassess the property.
Insurance for Residential Rental Property
Do not use a homeowner's policy
A standard homeowner's policy (often called an HO-3) is written for a house the owner lives in. Most homeowner's policies either exclude or sharply limit coverage when the house is rented to someone else, and they typically exclude liability arising from business activities. Renting property is a business. A rental house owned by an LLC and insured under the member's homeowner's policy is a claim denial waiting to happen.
Landlord policy (dwelling fire policy)
Residential rental property with one to four units is usually insured under a dwelling fire policy, often called a landlord policy. The three common forms are:
- DP-1 (basic). Covers a short list of named perils such as fire, lightning and explosion, often at actual cash value. Cheap, and usually too thin for a property with a mortgage or real equity.
- DP-2 (broad). Adds more named perils such as wind, hail, weight of snow and accidental water discharge. Often pays replacement cost on the building.
- DP-3 (special). Covers the building against all risks of direct physical loss except those specifically excluded, usually at replacement cost. This is the form most of our clients should ask for.
A landlord policy does not automatically include liability coverage. Premises liability is often a separate endorsement or a separate policy. Ask for it by name and confirm the LLC is the insured on it.
Coverages every residential rental policy should have
- Dwelling coverage at replacement cost. Insure the building for what it would cost to rebuild today, not what you paid for it and not its market value. Land is not insured because it does not burn.
- Other structures. Detached garages, casitas, block walls, fences and sheds.
- Fair rental value (loss of rents). Pays the rent you lose while a covered loss is being repaired. Without it, the LLC still owes the mortgage payment on a building no one can live in.
- Premises liability. Pays for injuries to tenants, guests and others on the property, plus the cost of defending the lawsuit.
- Ordinance or law coverage. Older Arizona properties rebuilt after a loss must meet current building codes. Standard policies often do not pay for the code upgrade.
- Landlord's contents. Appliances, window coverings and furniture the LLC owns and leaves in the unit.
- Vandalism and malicious mischief. Often limited or excluded when the unit is vacant. See the vacancy section below.
Apartment buildings with five or more units
Properties with five or more units are usually insured under a commercial property policy and a commercial general liability policy, often packaged together as a commercial package policy. The concepts are the same; the forms are commercial forms.
Require your tenants to carry renter's insurance
Your policy does not cover the tenant's furniture, clothing or electronics. A good lease requires the tenant to carry renter's insurance with personal liability coverage and to name the LLC as an interested party so the LLC is notified if the policy lapses. If a tenant's space heater starts a fire, the tenant's liability coverage can pay for damage to the LLC's building, which protects your loss history and your premiums.
Swimming pools, dogs and other high-risk features
Arizona rental houses often come with pools. Pools increase liability risk and some insurers exclude diving boards and slides. Arizona has a statewide pool barrier law for certain residential pools, A.R.S. §36-1681, and many cities have stricter ordinances. Make sure the pool is disclosed on the application, the barrier complies with the law, and the liability limits are high enough. Also ask whether the policy excludes injuries caused by tenants' dogs; many landlord policies do, and some exclude specific breeds.
Short-Term Rentals and Vacation Rentals
An LLC that rents a house on Airbnb or VRBO has a different risk profile than an LLC with a one-year tenant. Guests change every few days, they are unfamiliar with the property, and there may be a pool, a hot tub, an outdoor fire pit and a crowd. Most standard landlord policies exclude or limit short-term rental activity. You need a policy written specifically for short-term rentals, or a landlord policy with a short-term rental endorsement.
Arizona's short-term rental insurance rule
Arizona limits how much cities, towns and counties may regulate short-term rentals, but it expressly lets them require liability insurance. Under A.R.S. §9-500.39 (cities and towns) and A.R.S. §11-269.17 (counties), a local government may require each vacation rental or short-term rental to maintain liability insurance appropriate to cover the rental in the aggregate of at least $500,000, or to advertise and offer the rental through an online lodging marketplace that provides equal or greater coverage. Many Arizona cities, including Scottsdale and Phoenix, have short-term rental permit ordinances. Check the ordinance in the city where your property is located before your first booking.
Do not rely on the platform's coverage alone
Airbnb's Host Liability Insurance program states a limit of $1,000,000 per stay and says it covers hosts, co-hosts and, in some cases, landlords and homeowners associations. That coverage has exclusions, it applies only to stays booked through that platform, and Airbnb's program summary says that for hosts with six or more active listings it may require contribution from other insurance or apply as excess coverage. Its damage protection for the building is a reimbursement program, not an insurance policy you control. Treat platform coverage as a backup, not your primary protection. The LLC should carry its own short-term rental policy that names the LLC as insured.
Condos and HOA Property
If the LLC owns a condominium unit, the condominium association carries a master policy. Under A.R.S. §33-1253, an Arizona condominium association must carry property insurance on the common elements (and on the units if the declaration requires it) and liability insurance for occurrences related to the common elements. The statute says the association's property insurance need not include improvements and betterments installed by unit owners or unit owners' personal property.
That leaves gaps the LLC must fill: the interior of the unit (depending on how the declaration defines what the association insures), upgrades such as flooring and cabinets, the landlord's contents, loss of rents, liability inside the unit, and loss assessment coverage in case the association's master policy deductible or an uninsured claim is assessed back to the owners. Ask your agent for a condo policy written for a rented unit, sometimes called a landlord condo policy or HO-6 with a rental endorsement, and give the agent a copy of the association's declaration and master policy summary.
If the LLC owns a house in a planned community (a regular HOA), the association usually insures only the common areas. The LLC insures the house.
Insurance for Commercial Real Estate
An LLC that owns an office building, retail center, warehouse or industrial property needs commercial forms:
- Commercial property insurance on the building, written on a special (all-risk) causes-of-loss form at replacement cost.
- Business income / rental income coverage to replace rent lost after a covered loss, ideally with an extended period of indemnity because commercial tenants can take months to return.
- Commercial general liability (CGL) for injuries and property damage on the premises.
- Equipment breakdown for HVAC, elevators, electrical and boilers.
- Ordinance or law coverage, which is especially important for older buildings.
- Commercial umbrella over the CGL.
The lease drives the insurance
In commercial real estate, the lease decides who insures what. Under a triple net lease, the tenant usually pays for the landlord's property insurance and carries its own liability coverage. Under a gross lease, the landlord usually buys the insurance and builds the cost into the rent. Either way, the lease should:
- Require the tenant to carry commercial general liability coverage in a stated minimum amount.
- Require the tenant's policy to name the LLC (and its manager and lender) as additional insureds.
- Require the tenant to insure its own improvements, fixtures and inventory.
- Include a mutual waiver of subrogation, so the landlord's insurer and the tenant's insurer cannot sue each other's insured after a loss, and confirm both policies allow it.
- Require the tenant to deliver certificates of insurance before move-in and on every renewal.
A certificate of insurance is only a snapshot. Calendar the renewal dates and ask for a new certificate every year. An expired tenant policy you never noticed is the same as no tenant policy.
How Much Liability Coverage Is Enough
There is no statute that tells an Arizona landlord how much liability insurance to carry (except the local short-term rental minimum discussed above). Your lender will set a floor. Your judgment should set the real number.
Start by asking what the LLC has to lose. The target of a lawsuit against an LLC is the equity in the property the LLC owns. At a minimum, the LLC's liability coverage should exceed that equity. Many owners of residential rentals carry at least $1,000,000 per occurrence, and commercial owners and short-term rental owners often carry more through an umbrella. Consider how many people are on the property, whether there is a pool or hot tub, whether guests change every few days, and how much a jury in your county might award for a serious injury.
Remember the defense costs too. Most liability policies pay the lawyer who defends the LLC in addition to the policy limits. That alone can be worth tens of thousands of dollars on a lawsuit you ultimately win.
Umbrella Policies and the LLC Gap
This is the gap we see most often. You have a $2,000,000 personal umbrella policy. You believe it covers your rental houses. It may not.
A personal umbrella policy sits on top of your auto and homeowner's policies and usually covers you and the members of your household. Many personal umbrella policies exclude or limit coverage for property owned by a business entity, or cover rental property only if it is scheduled on the policy and the underlying landlord policy carries a minimum liability limit. When the LLC owns the property, the LLC may not be an insured under your personal umbrella at all.
Your options:
- Ask your umbrella carrier to add the LLC as an additional named insured and schedule each rental property. Some carriers will do this for a small number of residential rentals.
- Buy a commercial umbrella policy in the LLC's name that sits over the LLC's landlord or commercial liability coverage.
- Get it in writing. Ask the agent to confirm by email that the umbrella covers liability arising from each property owned by the LLC, and keep the email.
Title Insurance After the Transfer
When you bought the property, you probably received an owner's title insurance policy that named you as the insured. When you deed the property to an LLC, the question is whether that policy continues to protect the new owner.
It depends on the policy form. The American Land Title Association 2021 Owner's Policy defines "Insured" to include the grantee of an Insured under a deed delivered without payment of actual valuable consideration if the grantee is an Affiliate of the Insured or a trustee or beneficiary of an estate planning trust. The ALTA 2006 Owner's Policy has a similar provision for a grantee wholly owned by the named insured. In plain English: if you deed the property for no consideration to an LLC that you (or you and your spouse, if you were both named insureds) wholly own, the policy generally continues to cover the LLC. The title company keeps every defense it would have had against you.
Watch out for these situations:
- Older policies. Owner's policies issued on forms before 2006 often do not extend coverage to a grantee LLC at all.
- The LLC is not wholly owned by the insured. If you add your children or a partner as members of the LLC, the LLC may not qualify as an affiliate.
- Only one spouse was the named insured. Compare the names on Schedule A with the members of the LLC.
Pull out your owner's policy, read Schedule A and the definition of "Insured," and if there is any doubt, ask the title company whether it will issue an endorsement adding the LLC as an insured. The cost is usually small compared to buying a new policy.
If the LLC is buying property directly, the LLC should be the named insured on the new owner's title policy from day one.
Workers' Compensation and Contractors
If the LLC has employees
Under A.R.S. §23-902, every person who employs any workers regularly employed is subject to Arizona's workers' compensation law, with an exception for domestic servants. If your LLC hires an on-site manager, a maintenance worker or a leasing agent, the LLC needs a workers' compensation policy.
Working members of the LLC get special treatment. Under A.R.S. §23-901, a working member who owns less than 50% of the membership interest is treated as an employee. A working member who owns 50% or more may be treated as an employee only if the insurance carrier accepts that in writing.
If the LLC hires contractors
Roofers, plumbers, landscapers and handymen get hurt on rental properties. Under A.R.S. §23-902(B), when a business procures work through a contractor over whose work it retains supervision or control, and the work is part of the business, the contractor and its employees can be treated as employees of the business. Protect the LLC by hiring licensed contractors, getting a certificate of insurance showing both general liability and workers' compensation coverage before work starts, and asking to be named as an additional insured on the contractor's liability policy for larger jobs. A written independent contractor agreement that complies with A.R.S. §23-902(D) helps too.
Vehicles
If you drive your personal car to collect rent or pick up supplies, your personal auto policy is usually primary. If the LLC owns a truck, the truck needs a commercial auto policy in the LLC's name. If employees drive their own cars on LLC business, ask about hired and non-owned auto coverage.
Coverage Gaps That Cause Claim Denials
Vacancy
Most property policies restrict coverage when a building has been vacant for more than a stated period, commonly 60 consecutive days. Vandalism, glass breakage, water damage and theft coverage may be suspended, or the payment reduced. If the LLC's property will be vacant for an extended period during a remodel or between tenants, tell the agent and buy a vacancy endorsement or a vacant dwelling policy.
Flood
Standard property policies exclude flood. Arizona's monsoon season produces flash floods in neighborhoods that are not in a mapped flood zone. Flood insurance is available through the National Flood Insurance Program and private carriers. NFIP policies generally have a 30-day waiting period before coverage starts, so do not wait until the forecast turns bad.
Wind and hail deductibles
Arizona monsoon storms damage roofs. Some policies carry a separate wind/hail deductible stated as a percentage of the dwelling limit rather than a flat dollar amount. A 2% deductible on a $500,000 dwelling limit is $10,000. Know your number.
Actual cash value on the roof
Some carriers pay only the depreciated value of an older roof, even on a replacement cost policy. Read the roof schedule or endorsement.
Wrong use or misrepresentation
If the application says the property is a long-term rental and the LLC runs it as an Airbnb, or the application says there is no pool, a claim can be denied. Tell the agent the truth about how the property is used and update the agent when that changes.
Mold, sewer backup and slow leaks
These are commonly excluded or sub-limited. Sewer and drain backup coverage is usually an inexpensive endorsement worth buying.
Tenant damage
Ordinary wear and tear and damage caused intentionally by a tenant are often excluded or limited. Your protection is a good lease, a security deposit, a move-in inspection and the tenant's renter's insurance. Some carriers sell a malicious damage by tenant endorsement.
One LLC or Many, One Policy or Many
Many of our clients own several rental properties and form a separate LLC for each one, so a lawsuit over one property cannot reach the equity in the others. That structure is sound, but the insurance must match it.
- Each LLC should be a named insured for the property it owns. An agent can often write a single policy that schedules several properties and lists each LLC as a named insured. That is convenient and can reduce premiums.
- Watch the shared aggregate. A blanket liability policy covering several LLCs may have one aggregate limit for all of them. A catastrophic loss at one property can use up coverage that the other properties were counting on. Ask whether the aggregate applies per location.
- Keep the LLCs separate in every other respect. Separate bank accounts, separate leases, separate books. Insurance paid by one LLC for another LLC's property should be allocated and reimbursed.
If you use a holding company that owns several property LLCs, the holding company and each subsidiary LLC should all appear as named insureds.
Insurance Checklist for a Real Estate LLC
- The exact legal name of the LLC is the first named insured on the property and liability policies.
- Every member and the manager are additional insureds on the liability policy.
- The policy form fits the use: landlord (dwelling fire) for one to four residential units, short-term rental policy for vacation rentals, commercial forms for commercial property and five-plus units.
- The building is insured at replacement cost, with ordinance or law coverage.
- Loss of rents or business income coverage is included.
- Liability limits exceed the equity in the property, and an umbrella that covers the LLC sits on top.
- The lender is listed as mortgagee, and the property manager as an additional insured.
- Short-term rentals meet the local $500,000 minimum under A.R.S. §9-500.39 or §11-269.17 through the LLC's own policy.
- Pools, trampolines, dogs and other risks are disclosed on the application.
- Flood, sewer backup and vacancy coverage have been considered and purchased if needed.
- Leases require tenants to carry insurance and name the LLC.
- Contractors provide certificates of general liability and workers' compensation insurance before work starts.
- The owner's title policy covers the LLC, or an endorsement has been requested.
- Declarations pages and certificates are kept with the LLC's records and reviewed at every renewal.
Frequently Asked Questions
Does my LLC replace the need for insurance on my rental property?
No. The LLC protects your personal assets from the LLC's debts. Insurance protects the property inside the LLC and pays the lawyers who defend the lawsuit. You need both.
Can I keep the insurance in my own name after I deed the property to my LLC?
You should not. Once the LLC owns the property, you no longer do, and a policy that names only you may not cover the LLC's liability or may lead to a fight over the property claim. Ask your agent to make the LLC the named insured effective the day the deed records.
Will my insurance premium go up when the LLC becomes the insured?
Sometimes a little, sometimes not at all. If the property was wrongly insured under a homeowner's policy, the right landlord policy may cost more because it covers a rental risk the homeowner's policy never covered. That is not a price increase; it is the price of real coverage.
Is a homeowner's policy good enough for a house my LLC rents out?
No. Homeowner's policies are written for owner-occupied homes and typically exclude or limit coverage for rented dwellings and business activities. Use a landlord (dwelling fire) policy, preferably a DP-3.
What is the difference between a DP-1, DP-2 and DP-3 policy?
A DP-1 covers a short list of named perils, often at actual cash value. A DP-2 covers a broader list of named perils. A DP-3 covers all risks of direct physical loss except those excluded, usually at replacement cost. Most rental property owners should buy a DP-3.
Who should be listed as additional insureds?
The members and manager of the LLC, the property management company, and, for commercial property, anyone the lease or loan documents require. The lender is listed as mortgagee on the property coverage.
How much liability insurance should my real estate LLC carry?
Enough to protect the equity in the property, plus a cushion for a serious injury claim. Many residential landlords carry at least $1,000,000 per occurrence and add an umbrella. Short-term rentals and properties with pools warrant higher limits.
Does my personal umbrella policy cover property owned by my LLC?
Often it does not, unless the carrier has added the LLC as an insured and scheduled the property. Ask your agent to confirm coverage in writing, or buy a commercial umbrella in the LLC's name.
Does Arizona require landlords to carry insurance?
Arizona has no statute requiring a long-term residential landlord to carry insurance. Your lender will require property insurance. Cities, towns and counties may require short-term rental owners to carry at least $500,000 of liability coverage, or to rent through a platform that provides equal or greater coverage.
Is Airbnb's AirCover enough for my short-term rental LLC?
It should not be your only coverage. It applies only to stays booked through that platform, it has exclusions, and Airbnb says it may apply as excess coverage for hosts with six or more listings. The LLC should carry its own short-term rental policy.
Can I require my tenants to carry renter's insurance?
Yes, through the lease. Require personal liability coverage in a stated amount and require the tenant to list the LLC as an interested party so the LLC is notified if the policy is cancelled.
My LLC owns a condo. Doesn't the HOA's master policy cover it?
Only partly. Under A.R.S. §33-1253, the association's property insurance need not cover improvements and betterments installed by unit owners or unit owners' personal property. The LLC needs its own condo policy for the interior, upgrades, liability inside the unit, loss of rents and loss assessments.
What happens to my title insurance when I deed my property to my LLC?
Under the ALTA 2021 and 2006 owner's policy forms, coverage generally continues for an LLC wholly owned by the named insured that receives the property without paying for it. Older forms may not extend coverage. Check your policy and ask the title company for an endorsement if there is any doubt.
Does my LLC need workers' compensation insurance?
If the LLC regularly employs anyone, yes. A working member who owns less than 50% of the LLC counts as an employee. A working member who owns 50% or more is covered only if the carrier accepts it in writing.
What should I get from contractors before they work on my rental?
Confirm the contractor is licensed and get a certificate of insurance showing general liability and workers' compensation coverage. For larger jobs, ask to be named an additional insured on the contractor's liability policy.
What happens if my rental house sits vacant?
Most policies restrict coverage after a stated vacancy period, often 60 consecutive days. Tell your agent before the property goes vacant and buy a vacancy endorsement or vacant dwelling policy if needed.
Do I need flood insurance in Arizona?
Standard policies exclude flood, and monsoon flash floods reach properties outside mapped flood zones. If the property is in or near a wash or low-lying area, buy flood insurance. NFIP policies generally have a 30-day waiting period.
Should each of my rental LLCs have its own insurance policy?
Each LLC must be a named insured for the property it owns, but one policy can often schedule several properties and several LLCs. Watch for a shared aggregate liability limit that one bad claim could exhaust.
What is loss of rents coverage?
It pays the rent the LLC loses while a covered loss is being repaired. Without it, the LLC may still owe the mortgage, taxes and HOA dues while collecting no rent.
What is ordinance or law coverage?
It pays the extra cost of rebuilding to current building codes after a covered loss. Older properties often need it because code upgrades can add a large amount to a rebuild.
Does the LLC protect me if I personally cause an injury on the property?
No. You are always liable for your own negligence. That is why members and the manager should be additional insureds on the LLC's liability policy.
If I sell a rental property, when do I cancel the insurance?
Not until the deed to the buyer records and escrow closes. Cancel effective the closing date, and keep the liability policy records, because claims can be filed after the policy period for incidents that occurred during it.
Does a revocable trust that owns my LLC affect the insurance?
Not the property policy, because the LLC still owns the property and remains the named insured. If your trust owns the LLC membership interest, consider asking the agent to add you as trustee as an additional insured. If the trust owns real estate directly rather than through an LLC, the trustee should be the named insured.
How often should I review the LLC's insurance?
At every renewal, whenever you transfer property into or out of the LLC, whenever the use changes (long-term to short-term rental, residential to commercial), and after any major renovation that increases replacement cost.
How KEYTLaw Can Help
We are lawyers, not insurance agents, and we do not sell insurance. What we do is form Arizona LLCs that own real estate, prepare the deeds that move property into them, and write operating agreements that fit the way real estate investors actually operate. We tell every real estate client to call an insurance agent before the deed records, and we explain exactly what to tell the agent.
We prepare a special warranty deed to convey Arizona real property to an LLC for a $295 flat fee. Submit our deed preparation questionnaire to get started. You can also book a free office, phone or Zoom video consultation, and see more resources in our Arizona LLC Center.
Arizona LLC attorneys Richard Keyt and his son, attorney and former CPA Richard C. Keyt, have formed 10,000+ Arizona LLCs.
See the contents of our Bronze, Silver & Gold LLC packages.
To hire us to form an LLC submit our online questionnaire at keytlaw.com/llcq, call 480-664-7478 or email rk@keytlaw.com.
This article provides general information about Arizona law and insurance concepts. It is not legal advice or insurance advice. Insurance policy terms vary by carrier and form; read your own policy and consult a licensed insurance professional about coverage.
We want to form your Arizona LLC or PLLC
- To get free answers to your LLC questions call Arizona LLC attorneys Richard Keyt (480-664-7478 & rk@keytlaw.com) or his son Richard C. Keyt (480-664-7472 & rck@keytlaw.com).
- 60+ articles about Forming & Operating Arizona LLCs
- Book a free office, phone or Zoom video meeting to get answers to your LLC questions
- See the contents & prices of our 3 LLC formation packages
- Submit our LLC formation questionnaire to hire us to form your AZ LLC today
Questions? Book a free meeting or call or email one of our Arizona estate planning attorneys. We don't charge to talk to people.
Updated September 26, 2026
Call, email or text Richard Keyt, father
Direct phone: 480-664-7478
Email: rk@keytlaw.com
Call, email or text Richard C. Keyt, son
Direct phone: 480-664-7472
Email: rck@keytlaw.com